Tips and support
S&P 500 Investment Calculator: Calculate Historical DCA Returns

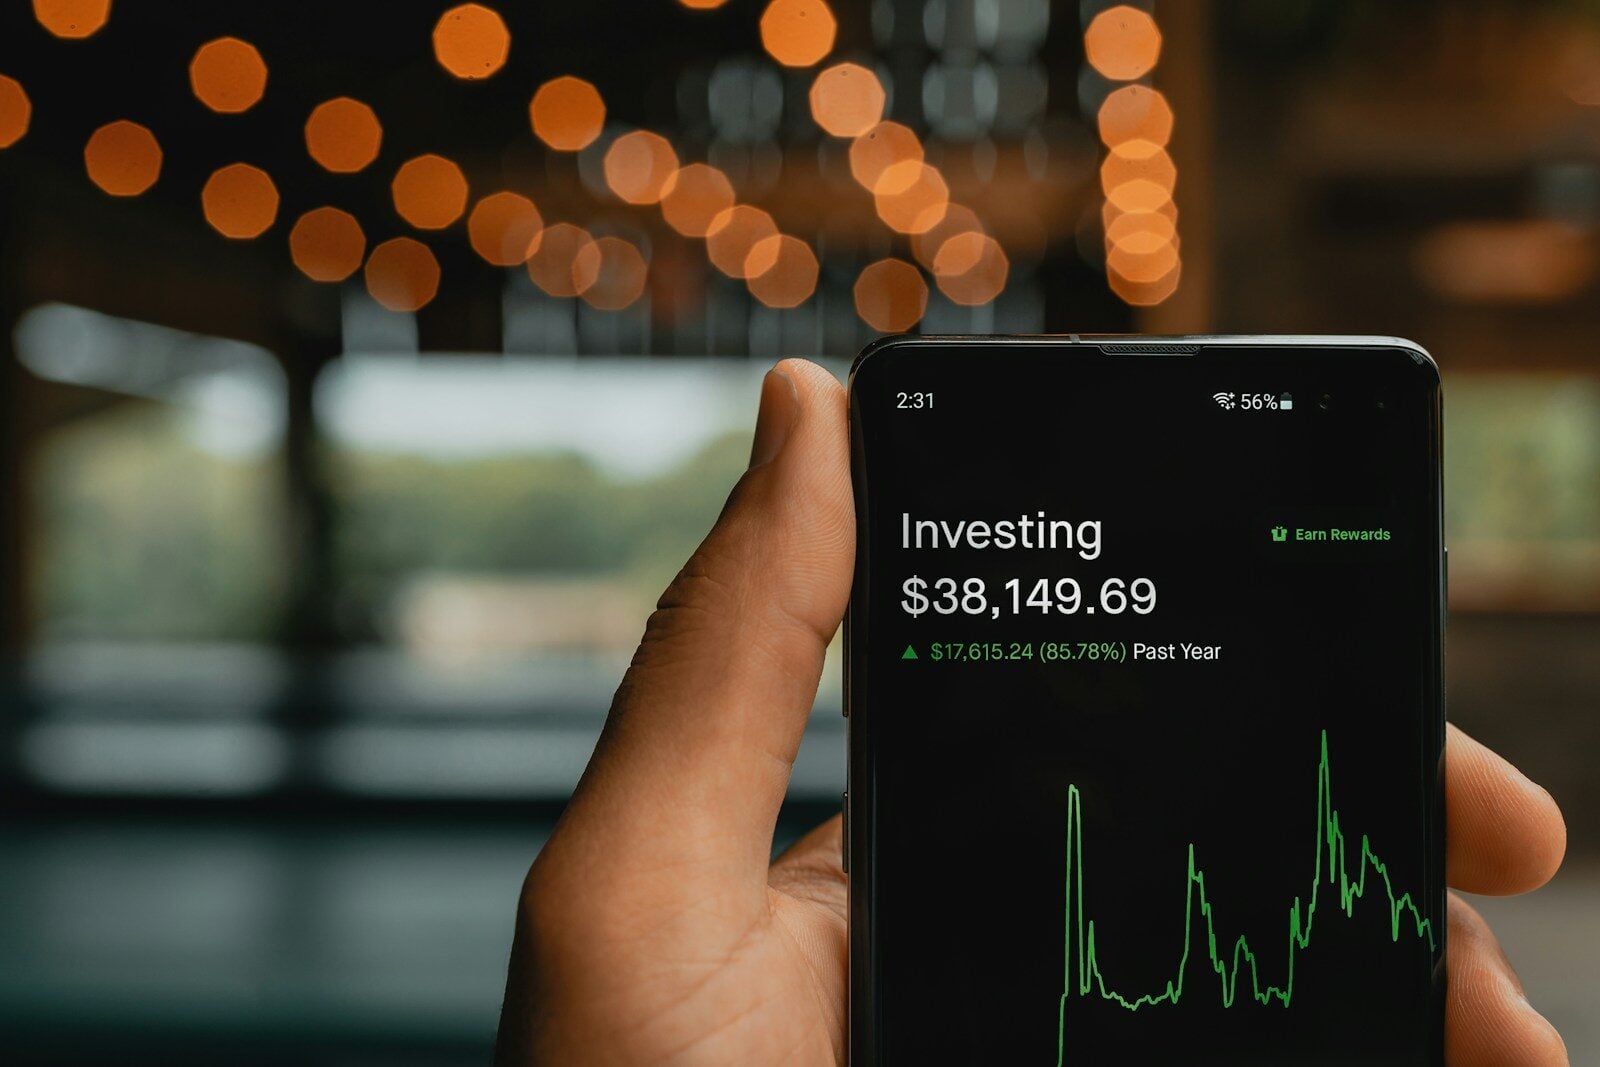
An S&P 500 investment calculator can help you understand how a regular investment strategy would have performed during different historical periods. If you want to calculate the historical results of investing a fixed amount into the S&P 500 on a regular schedule, you can use the S&P 500 investment calculator to enter your contribution amount, investment dates, frequency and other parameters.
Instead of relying on a single average return, a historical DCA calculator allows you to look at a specific investment period and see how regular contributions would have developed over time.
What Is an S&P 500 Investment Calculator?
An S&P 500 investment calculator is a tool that uses historical market data to estimate how an investment strategy would have performed in the past.
The basic idea is simple.
You choose an investment period and specify how much you would have invested. The calculator then applies historical market prices to estimate the value of the investment over that period.
For example, you could enter:
- Start date: January 2010
- End date: January 2020
- Contribution: $500
- Frequency: Monthly
- Initial investment: $0
The result can then be compared with the total amount you contributed.
This type of calculation can be particularly useful for investors who are interested in dollar-cost averaging.
What Is Dollar-Cost Averaging?
Dollar-cost averaging, usually abbreviated as DCA, is an investment strategy where you invest a fixed amount at regular intervals.
For example, an investor might decide to invest $500 into an S&P 500 fund every month.
The investor contributes the same amount regardless of whether the market is going up or down.
When prices are high, the contribution purchases fewer shares or ETF units.
When prices are lower, the same contribution purchases more.
Over time, the investor accumulates investments at different prices instead of making one large purchase at a single price.
This makes DCA particularly suitable for people who invest part of their regular income.
Why Use Historical DCA Calculations?
One of the biggest advantages of a historical calculator is that it allows you to test a specific investment scenario.
Instead of asking:
“What is the average return of the S&P 500?”
you can ask:
“What would have happened if I invested $500 every month from January 2010 to January 2020?”
These are different questions.
An average annual return does not show exactly how a series of monthly contributions would have performed.
With DCA, every contribution enters the market at a different price.
The timing of those contributions therefore matters.
How Does an S&P 500 DCA Calculator Work?
A typical calculation requires several inputs.
Start Date
The start date determines when your investment plan begins.
For example, you could start in January 2000, January 2010 or January 2020.
Changing the start date can produce significantly different historical results.
End Date
The end date determines how long the investment strategy runs.
You could analyze a five-year, ten-year, twenty-year or longer period.
Amount Per Contribution
This is the amount invested each time.
For example:
- $100 per month
- $250 per month
- $500 per month
- $1,000 per month
You can use the same calculator to test different contribution levels.
Initial Investment
Some investors start with a lump sum before beginning regular contributions.
For example, you might start with $10,000 and then invest $500 every month.
Including the initial investment allows you to analyze this type of strategy.
Frequency
The frequency determines how often you invest.
Common choices include:
- Weekly
- Monthly
- Quarterly
Changing the frequency changes the timing of individual purchases.
Currency
The currency is another useful parameter, particularly for investors outside the United States.
An investor in Europe might think about their investments in EUR, while the underlying S&P 500 market is commonly quoted in USD.
Currency movements can therefore become an additional consideration for international investors.
Nominal vs. Real Returns
When analyzing historical investment performance, it is important to understand the difference between nominal and real returns.
Nominal returns represent the investment value without adjusting for inflation.
Real returns account for the effect of inflation.
This distinction becomes increasingly important over long investment periods.
For example, an investor may see that a portfolio grew from $50,000 to $100,000.
That represents a significant nominal increase.
However, the purchasing power of $100,000 in the future may be lower than the purchasing power of $100,000 today.
Looking at inflation-adjusted results can therefore provide additional context.
Total Contributions vs. Portfolio Value
One of the most useful parts of a DCA calculation is comparing the amount invested with the final portfolio value.
Suppose you invest:
$500 × 12 months × 20 years = $120,000
Your total contributions would therefore be $120,000.
If the historical calculation shows a final portfolio value above $120,000, the difference represents investment growth before considering any additional factors such as taxes, fees or differences between the theoretical index and an actual investment product.
This simple comparison helps demonstrate the role of investment returns over time.
Why the Starting Date Is Important
The S&P 500 does not produce the same return every year.
There are periods of strong growth as well as periods of significant declines.
Consider an investor who starts a DCA strategy shortly before a major market correction.
The first part of the investment period may show disappointing results.
However, the investor continues making regular contributions while prices are lower.
Now consider an investor who starts during a period of rapidly rising prices.
Their initial contributions may increase in value quickly, but subsequent contributions may be made at higher prices.
These differences illustrate why historical DCA results depend heavily on the exact dates selected.
DCA During a Market Crash
Market crashes are an important part of historical investment analysis.
When the S&P 500 falls, the value of existing investments declines.
For an investor using DCA, however, future contributions continue to be invested.
Suppose an investor contributes $500 every month.
If an investment costs $100 per share, the contribution buys approximately five shares.
If the price later falls to $50, the same $500 buys approximately ten shares.
The investor is therefore purchasing more units while prices are lower.
Of course, there is no guarantee that the market will recover quickly or that every investment will eventually increase in value.
But regular contributions make the strategy fundamentally different from investing a single lump sum at one specific point in time.
DCA vs. Lump-Sum Investing
An S&P 500 investment calculator can also be useful for comparing DCA with lump-sum investing.
Consider an investor with $60,000.
They could invest the entire $60,000 immediately.
Alternatively, they could spread the money over several years through regular contributions.
The two strategies have different market exposure.
With a lump-sum investment, the entire amount is invested immediately.
With DCA, the money enters the market gradually.
If the market rises after the initial investment, the lump-sum approach has more capital exposed to that growth.
If the market declines, the lump-sum investor experiences the decline on the entire initial investment.
Historical comparisons can show how these strategies behaved during specific periods.
However, historical results do not guarantee that either strategy will produce the same outcome in the future.
How Long Should You Analyze?
There is no single correct investment period for a historical calculation.
You can analyze different periods depending on the question you are trying to answer.
For example:
5 years: Useful for examining a relatively recent period.
10 years: Provides a longer perspective across multiple market conditions.
20 years: Shows how a strategy behaved through multiple market cycles.
30 years: Provides an even longer historical perspective.
Comparing several periods can be more informative than looking at only one.
For example, you could calculate the same $500 monthly contribution over 10, 20 and 30 years and compare the results.
How Much Should You Invest?
An investment calculator can also help you understand how contribution size affects the final portfolio.
Consider three hypothetical monthly contributions:
| Monthly contribution | Annual contribution | Contribution over 20 years |
|---|---|---|
| $100 | $1,200 | $24,000 |
| $500 | $6,000 | $120,000 |
| $1,000 | $12,000 | $240,000 |
These figures do not include investment returns.
They simply demonstrate how contribution amounts accumulate over time.
A higher monthly contribution means more money is invested, but investors should always consider their own budget, emergency savings and financial objectives before deciding how much to invest.
The Importance of Time
Investment calculators also demonstrate the potential importance of a long investment horizon.
Suppose two investors contribute the same amount every month.
One invests for 10 years.
The other invests for 30 years.
The second investor contributes three times as much money, but there is another difference: earlier contributions have more time to potentially grow.
This is where compounding becomes relevant.
Investment gains that remain invested can potentially generate additional gains over time.
The effect can become increasingly significant as the investment period becomes longer.
What About Dividends?
The S&P 500 consists of companies that may pay dividends.
When analyzing historical returns, it is important to understand whether the calculation uses price returns or total returns.
Price return measures changes in the prices of the underlying stocks.
Total return includes dividends and assumes they are reinvested.
For a long-term investor, this distinction can be important.
An investor using an actual ETF may also experience expenses, tracking differences and other costs that are not necessarily reflected in a simple index calculation.
Therefore, a historical calculator should be viewed as an approximation of how a strategy would have behaved under its stated assumptions.
S&P 500 Index vs. S&P 500 ETF
The S&P 500 itself is an index rather than an investment product.
Investors generally gain exposure to the index through mutual funds or ETFs.
There are many S&P 500 ETFs available around the world.
For European investors, for example, UCITS ETFs can provide exposure to the S&P 500 while following European regulatory requirements.
One example is CSPX, an accumulating S&P 500 ETF from iShares.
The historical performance of a specific ETF may differ from the theoretical performance of the index because of factors such as:
- Fund expenses
- Tracking difference
- Taxes
- Currency effects
- Trading costs
- Dividend treatment
For this reason, investors should distinguish between an index calculation and the actual return of a particular fund.
How to Use an S&P 500 Investment Calculator
A simple historical DCA calculation can be completed in several steps.
Step 1: Choose the Start Date
Select the date when you want your hypothetical investment plan to begin.
Step 2: Choose the End Date
Select the date when the calculation should finish.
Step 3: Enter the Contribution
Enter the amount you would invest at each interval.
Step 4: Select the Frequency
Choose weekly, monthly or another available contribution frequency.
Step 5: Add an Initial Investment
If you want to simulate starting with a lump sum, enter the initial amount.
Step 6: Select Nominal or Real Returns
Choose whether you want to see the historical result before or after inflation adjustment.
Step 7: Review the Results
Look at the total contributions, final portfolio value and investment growth.
You can then change one variable at a time and see how the historical outcome changes.
Experiment With Different Scenarios
The most useful feature of a historical calculator may not be the result of one particular scenario.
It is the ability to experiment.
For example, you could compare:
- $100 vs. $500 monthly
- Monthly vs. weekly contributions
- 10-year vs. 20-year periods
- Different starting dates
- With and without an initial investment
- Nominal vs. real returns
- DCA vs. lump-sum investing
This allows you to understand how different assumptions affect the historical outcome.
You can run these scenarios with an S&P 500 DCA calculator and use the results to explore different historical investment plans.
Important Limitations
Historical investment calculations have several limitations.
First, historical performance does not guarantee future results.
Second, a theoretical index calculation may not exactly match the return of an actual investment product.
Third, taxes and fees can reduce actual returns.
Fourth, currency movements can affect investors whose base currency is not the U.S. dollar.
Finally, the calculation is based on historical data and assumptions. Changing the contribution date, frequency or other parameters can change the result.
For these reasons, a calculator should be considered an educational and analytical tool rather than a prediction of future investment performance.
Final Thoughts
An S&P 500 investment calculator provides a practical way to explore how regular investing would have performed during historical periods.
Dollar-cost averaging is particularly easy to model because the strategy follows a simple rule: invest a predetermined amount at regular intervals.
The final historical outcome depends on several factors, including the start date, end date, contribution amount, frequency, initial investment and market performance.
Inflation is another important consideration, which is why comparing nominal and real returns can provide additional context.
Instead of asking only what the S&P 500 returned on average, investors can use historical DCA calculations to answer more specific questions:
What if I invested $100 every month?
What if I invested $500?
What if I started 10 years ago?
What if I invested weekly instead of monthly?
How did DCA compare with a lump-sum investment?
These questions can provide a more practical understanding of how a long-term investment strategy interacts with changing market prices.
Historical data cannot predict the future, but it can help investors understand the mechanics of regular investing and the potential impact of contribution size, investment period and market conditions.


-

 Resources5 years ago
Why Companies Must Adopt Digital Documents
-

 Resources4 years ago
A Guide to Pickleball: The Latest, Greatest Sport You Might Not Know, But Should!
-

 Resources1 year ago
50 Best AI Free Tools in 2025 (Tried & Tested)
-

 Resources1 year ago
Get Paid $5000+ a month to write : Discover 30 Spectacular Websites That Reward Your Writing Effort