Blogs
What Happens to Joint Debt During a Divorce?

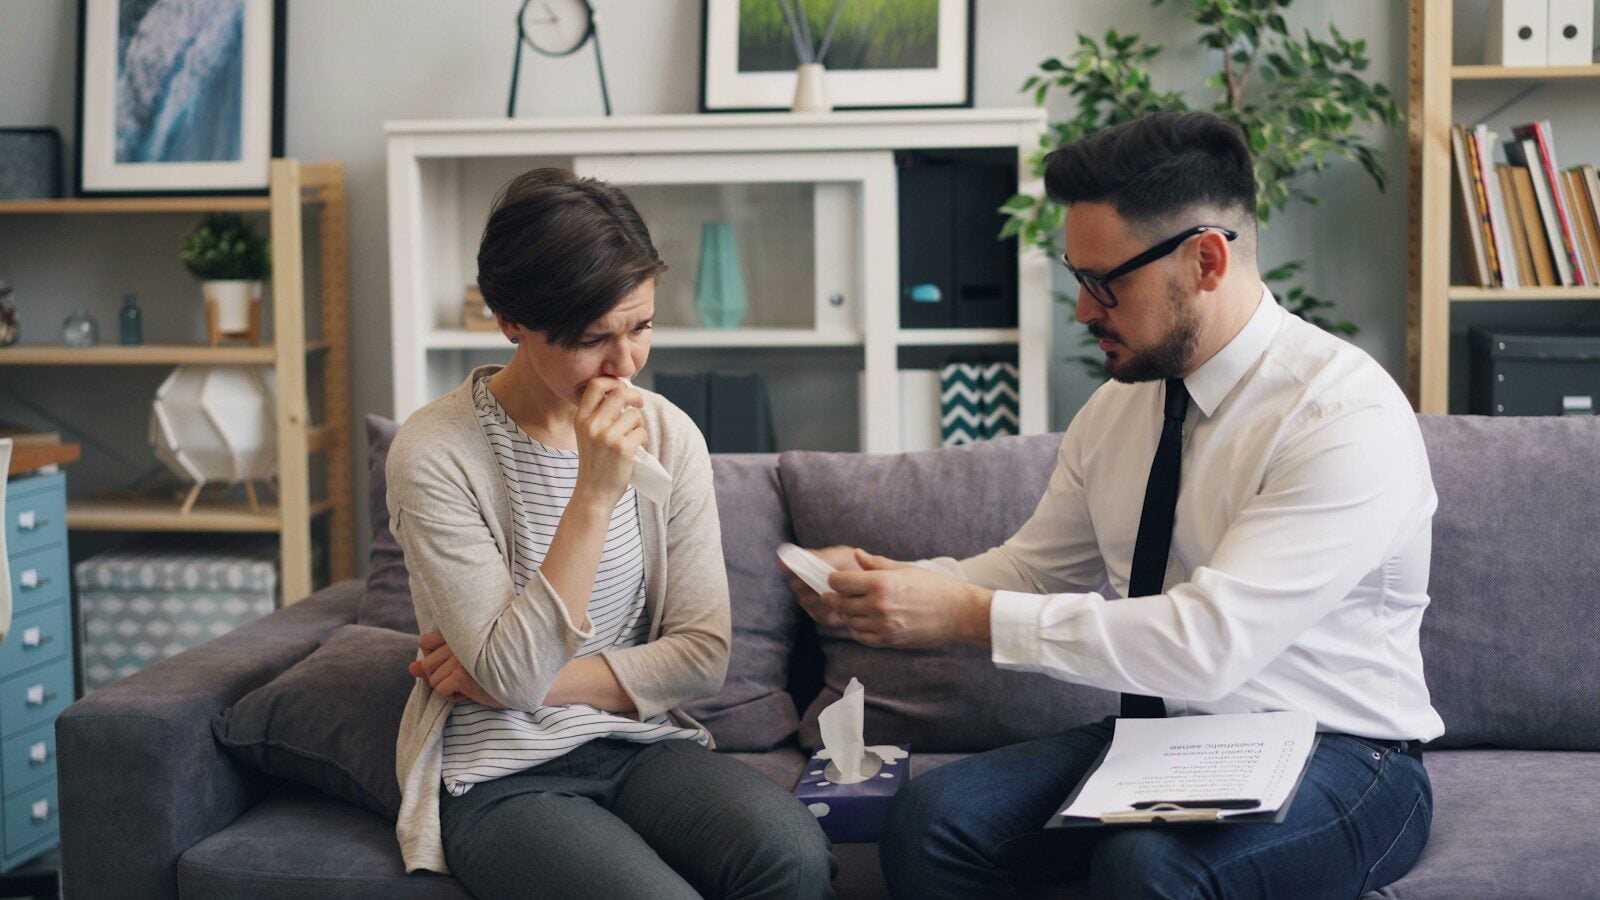
Divorces affect every aspect of your life. From deciding who gets your house and vehicles to child custody matters. There are many steps involved. One that you may not think about right away is your joint debt. Joint mortgages, car loans, personal loans, credit cards, and other shared obligations are a major part of the property division process.
An initial divorce decree doesn’t automatically remove either spouse from joint debt. However, it’s important to note that a court can order one spouse to pay a particular debt. This court order doesn’t alleviate both spouses from legal responsibility with the creditor. Rather, both spouses will remain legally responsible for the account, and the creditor can pursue either person if there are missed payments.
Understanding Joint Debt
Simply defined, joint debt refers to financial obligations for which both spouses are legally responsible. Common examples are joint credit cards or loan accounts where both parties agree to repay the balance. In some cases, one spouse may be an authorized user instead of a joint borrower. In cases of an authorized user, that particular person doesn’t have the same contractual responsibility as the borrower.
Joint debt can include many different accounts. Some typical ones you may address during your divorce proceedings include personal loans, auto loans, home equity loans, mortgages, and joint credit cards. The very first step in any divorce is determining what debts are actually joint and which ones aren’t. Just because you use an account during your marriage doesn’t necessarily make you legally responsible for repaying it.
How Does Joint Debt Get Divided?
Whenever you go through a divorce, the court has to address marital debts as part of the overall division of marital property. How your debts get divided up depends on the individual circumstances of your marriage as well as applicable state laws. Some states follow what’s known as community property rules, while others follow equitable distribution principles.
Knowing the differences between these two can help you better determine what applies to your situation. It’s always a good idea to consult an experienced divorce lawyer like the attorneys at Davis & Associates who can explain the specific laws that are applicable to your state. This can let you know if that debt must be divided equally or not.
Understanding Your Responsibility for Joint Debt
In most cases of joint debt, both parties are still legally responsible for the debt. For example, let’s say that you and your spouse had a $10,000 credit card debt. Just because the judge orders your ex-spouse to pay off that $10,000 credit card debt, that doesn’t remove you from your legally binding agreement with the credit card provider.
In the event that your ex-spouse stops making payments, the creditor could still have the legal right to pursue you for the remaining balance. It’s important to remember that the creditor isn’t necessarily a party to the divorce proceedings. They don’t have to follow any agreement that changes a spouse’s responsibility to the other. A simple way to think about this is that the divorce court determines financial responsibilities between the two spouses, while the original credit agreement or loan governs the relationship with your creditor.
What Happens If Your Ex-Spouse Doesn’t Pay?
If your ex-spouse doesn’t pay their debt that’s required as part of your divorce agreement, you can still face consequences on your part. Missed payments can result in collection activity, late fees, additional interest, and even damage to your credit history. This is why it’s still important for you to be aware of the account status so you can identify any problems before they become serious.
While you’re still legally responsible for paying the creditor the initial debt that you owe them, you do have the opportunity to go back to Family Court to enforce your divorce agreement. The different available remedies really depend on your local state laws and the terms of your divorce judgment. Speaking with a divorce attorney can help you determine what your legal remedies are for a spouse that doesn’t pay.
What About Closing Joint Credit Cards?
A fairly common type of debt that many married couples have is joint credit cards. When going through a divorce, you may request the closure of a joint credit card to prevent additional debt from accumulating after your separation. But keep in mind, closing an account doesn’t actually eliminate its existing balance. You still have to pay back the entire balance according to the creditor’s terms.
One of the easiest ways to deal with joint credit cards where one party is responsible for paying off the entire debt is to do a balance transfer. Transferring the balance from a joint credit card to a personal credit card will allow the closure of the joint credit card and the balance to be paid off. One thing to keep in mind before closing any joint credit card is that both spouses need to understand how doing so will affect their credit.
Understanding What Happens to Mortgages
Another fairly common type of joint debt is a mortgage. Mortgages can be more complicated than just regular consumer debt because they’re secured by real estate. While your divorce may award your home to one spouse, that doesn’t necessarily remove the other spouse from the mortgage commitment.
For example, let’s say that the court awards the marital home to one spouse, and that spouse agrees to make all future mortgage payments. Unfortunately, if both spouses are borrowers on that mortgage, the lender can still come after the party that wasn’t awarded the home for repayment. A great way to handle mortgages is to have the party who was awarded the home refinance their mortgage under their own name. In other cases, couples may opt for selling their home and using the proceeds to pay off their mortgage.
A Look at Car Loans
Just like with the mortgage, a divorce court may award a particular vehicle to one party. That party may agree to pay off all the remaining payments for the car loan. However, both parties still remain legally liable until the loan is paid. This is where refinancing the vehicle into just the name of the spouse who keeps it can be particularly helpful.


-

 Resources5 years ago
Why Companies Must Adopt Digital Documents
-

 Resources4 years ago
A Guide to Pickleball: The Latest, Greatest Sport You Might Not Know, But Should!
-

 Resources1 year ago
50 Best AI Free Tools in 2025 (Tried & Tested)
-

 Resources1 year ago
Get Paid $5000+ a month to write : Discover 30 Spectacular Websites That Reward Your Writing Effort